“Sirf ₹1,999 mahina.” It is the line on the showroom standee, the poster, and the WhatsApp forward your cousin sent. And it is not wrong. But it is only one of three numbers that decide what an electric scooter on EMI really costs you. The second is what you pay on the day you sign. The third, the one nobody prints in big letters, is what you will have paid in total by the last instalment. This guide shows you how to find all three before you sign anything.
The short answer.
Yes, you can usually buy an electric scooter on EMI, through a lender your dealer works with, your own bank, or a card or pay-later plan. Before you sign, get three numbers in writing: what you pay upfront (down payment, fees and any advance EMIs), what you pay every month, and what you pay in total.
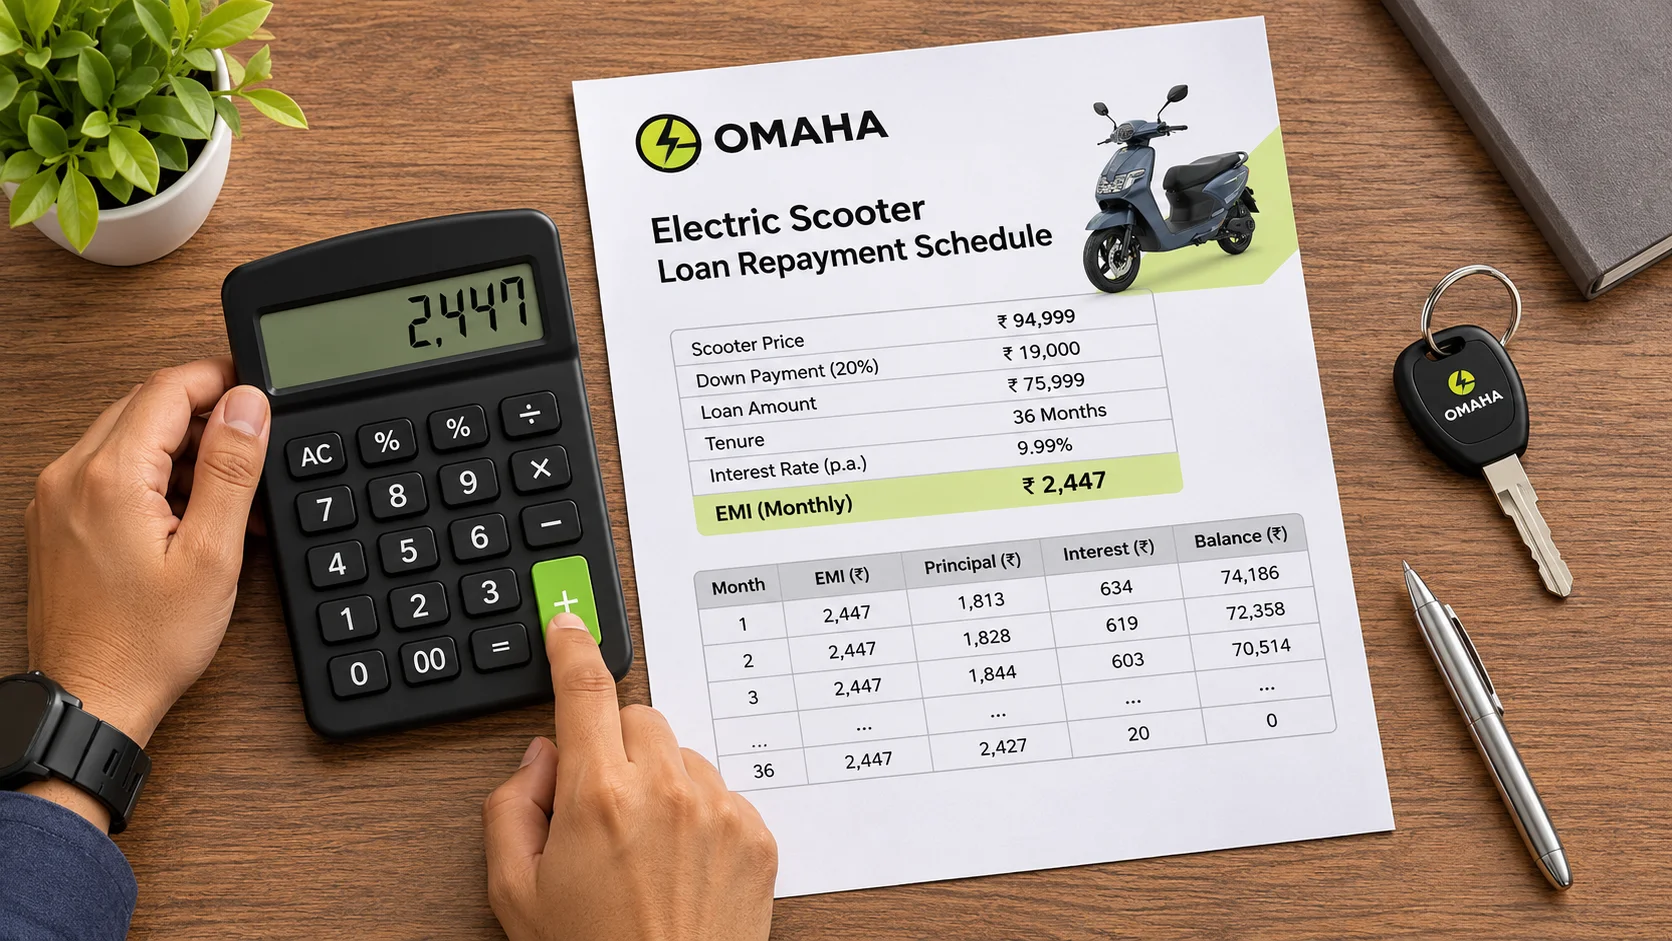
For a bank or NBFC loan, ask for the Key Facts Statement. It must show the all-inclusive annual rate and the repayment schedule. Then compare the total with the cash price on the Omaha price list, and ask your dealer which finance options they offer.
The three numbers that decide an EMI deal
1. What you pay upfront
This is more than the down payment. It can include a processing fee (usually with GST on top), documentation charges, insurance if the lender asks for it, and sometimes one or two EMIs collected in advance. Add every rupee you hand over on the day.
2. What you pay every month
The EMI itself. It depends on the loan amount, the interest rate and the tenure. A longer tenure lowers the EMI but almost always raises the total you pay.
3. What you pay in total
Upfront payment plus every EMI. Subtract the cash price, and what is left is the real cost of borrowing. This is the number to compare between offers, not the monthly figure.
Electric scooter EMI calculator
Enter the figures from your quote and see all three numbers together. The values filled in are only an example, so replace them with your own.
Uses the standard reducing-balance EMI formula. Lenders may round, charge interest from the disbursal date, or structure advance EMIs differently, so treat this as an estimate and rely on your lender’s repayment schedule.
Electric scooter EMI plan offers, decoded
Festive and showroom finance offers are often genuinely useful. They are also written to make the monthly figure look as small as possible. Here is what to ask about each common one.
| The offer says | What it usually means | Ask this |
|---|---|---|
| “Zero down payment” | Nothing towards the price on day one, but fees, insurance or advance EMIs may still be due | What exactly do I pay on the day I take the scooter? |
| “No-cost EMI” | The interest is covered by a discount you would otherwise get, or built into the price | Is the EMI price the same as the cash price? Is there a processing fee? |
| “EMI from ₹X a month” | Usually the longest tenure and the biggest down payment | For my down payment and tenure, what is the EMI and the total? |
| “Low interest rate” | The headline rate, before fees | What is the APR in the Key Facts Statement? |
| “Card EMI” or “pay later” | Converted on a credit card or app; terms differ from a regular loan | What interest, conversion fee and late charges apply? |
An offer that sounds good should still sound good once it is written down with all three numbers.
Your best friend in a loan: the Key Facts Statement
For retail loans from banks and NBFCs sanctioned since October 2024, the RBI requires lenders to give you a Key Facts Statement before you sign. It sets out the loan terms in a standard format, including the annual percentage rate (APR), which bundles the interest rate with the other charges, plus a computation sheet and a repayment schedule. Lenders cannot add fees that are not in it without your consent. These rules do not cover credit cards, so read card EMI terms separately.
How a low-speed scooter loan is different
This is something most guides to electric scooter finance in India miss. With a registered petrol or high-speed electric two-wheeler, the lender’s claim on the vehicle, called hypothecation, is recorded on the registration certificate, and removed after the last EMI. A low-speed electric scooter with a motor rated up to 250 W and a top speed up to 25 km/h needs no registration, so there is no RC to record it on.
That does not stop you getting finance, but it can change what kind of loan you are offered. Depending on the lender, it may be a two-wheeler loan with its own agreement, a consumer durable loan, a personal loan, or a card EMI. Each has different rates and rules, so ask:
- What type of loan is this, and who is the lender?
- How is the scooter secured, and what do I get as proof once the loan is closed?
- Can I sell or transfer the scooter before the loan ends?
Documents you will usually need
Each lender sets its own list, but most ask for some version of the following. Keep originals and clear photocopies ready.
- Identity proof — such as Aadhaar or PAN card.
- Address proof — such as Aadhaar, a utility bill or a rent agreement.
- Income proof — recent salary slips, bank statements or, if self-employed, income tax returns.
- Bank account details — for setting up automatic EMI payments.
- Photographs — passport size, if the lender asks.
- Dealer quotation — showing the model, battery and final price.
Your credit score will be checked. Lenders look at your repayment history before approving a loan. A weak score can mean a higher rate, a bigger down payment or a rejection. Each missed EMI afterwards also shows up on your credit record, which affects future loans.
From the showroom floor
A medical representative from Hisar came in with two offers on his phone: a low EMI over a long tenure, and a higher EMI over 12 months. He wanted the smaller monthly figure. We sat down with a calculator and added up both. The longer plan cost him noticeably more in total, for the same scooter. He chose the 12-month plan, saying he would rather have the scooter fully his before next Diwali.
Choosing the battery when you are buying on EMI
Every Omaha model comes with lead-acid or lithium. On the same model, lithium typically costs ₹10,000 to ₹15,000 more, and on EMI that difference is financed and charged interest. Lithium is lighter and charges in 3 to 5 hours rather than 6 to 8, which matters if the battery has to go upstairs. If you can charge at a ground-floor socket, lead-acid keeps both the loan and the EMI smaller. Our lead-acid vs lithium guide helps you decide by daily kilometres. Try both versions on the calculator above.
Can the savings pay part of the EMI?
Often, partly. If you currently spend on autos, shared rides or petrol, those costs drop once you ride an electric scooter, while you take on charging, which costs far less. A fair way to judge an EMI is to set it against your present monthly travel spend, not against nothing.
- Write down what you spend in a normal month on getting around.
- Estimate your charging cost: battery capacity in kWh (ask your dealer) × your electricity rate × charges per month.
- Compare the difference with the EMI.
For a city-specific example of fuel versus electric costs, see our Indore cost guide.
Only take an EMI you can pay in a bad month. Not your best month. If a medical bill, a fee or a slow month at work would make the EMI hard, choose a bigger down payment, a cheaper battery or a cheaper model, or wait and save a little longer. A missed EMI costs more than the scooter saves.
Before you sign: a seven-point check
- All three numbers in writing — upfront, monthly and total.
- Key Facts Statement received — with the APR and repayment schedule, for a bank or NBFC loan.
- EMI price matches the cash price — or you know exactly how much more you are paying.
- EMI dates — the first one, and the date each month, fit your salary or income cycle.
- Late payment charges — what they are, and how soon they apply.
- Early closure — whether you can pay off the loan early, and any charge for it.
- Read at home — take the papers home overnight if you can. A good offer will still be there tomorrow.
From the showroom floor
A young couple in Jaipur came in excited about a “zero down payment” plan they had seen elsewhere. When they asked for the full breakdown, the plan collected two EMIs, a processing fee and an insurance charge on the day of delivery. “Zero” was closer to a month’s salary. They did not walk away from EMI. They simply compared it against a plan with a modest down payment, which turned out cheaper in total.
The “From the showroom floor” stories are composite illustrations of common enquiry patterns, not individual customers’ accounts.
Get a quote you can calculate
Ask your nearest dealer for the cash price and the finance options, then put both into the calculator.
Conclusion: read the total, not the poster
Buying an electric scooter on EMI is a perfectly sensible way to spread the cost, especially when the scooter replaces money you already spend on autos or petrol. The trick is to look past the monthly figure. Find out what you pay on day one, what you pay every month, and what you pay in total, then compare that total with the cash price and with other offers.
Ask for the Key Facts Statement, keep the tenure as short as you can comfortably afford, and choose the battery with the EMI in mind. Then book a test ride, because the scooter should be the right one before the loan is.
Frequently asked questions
Can I buy an electric scooter on EMI?
Usually, yes. Finance may be available through a lender your dealer works with, your own bank, or a credit card or pay-later plan. Ask your dealer which options they offer, and compare the total cost of each against the cash price before you sign.
How much down payment is needed for an electric scooter?
It depends on the lender, the plan and your credit profile. Some plans ask for a share of the price upfront, while others advertise zero down payment but still collect fees or advance EMIs. Ask what you will pay in total on the day of delivery.
Is a zero down payment electric scooty really zero?
Not always. “Zero down payment” usually means nothing towards the scooter’s price on day one, but a processing fee, insurance or one or two advance EMIs may still be due. Ask for the complete upfront amount in writing.
What documents are needed for an electric scooter loan?
Most lenders ask for identity proof such as Aadhaar or PAN, address proof, income proof such as salary slips, bank statements or tax returns, bank account details for automatic EMI payments, and the dealer’s quotation. Each lender sets its own list.
Is no-cost EMI on an electric scooter really free?
No-cost EMI usually means the interest is covered by a discount you would otherwise receive, or included in the price. Check that the EMI price matches the cash price, and ask about any processing fee, which is often charged separately.
How is a low-speed electric scooter financed if it has no registration?
With registered vehicles, the lender’s claim is recorded on the registration certificate. Low-speed scooters have no registration certificate, so lenders may offer a two-wheeler loan with its own agreement, a consumer durable loan, a personal loan or a card EMI. Ask what type of loan it is and what proof you receive once it is closed.
What is a Key Facts Statement?
It is a standard summary of a retail loan’s terms that RBI-regulated lenders must give you, including the annual percentage rate, which combines interest and other charges, a computation sheet and the repayment schedule. It does not apply to credit cards.
Can I close my electric scooter loan early?
Often, yes, but terms vary. Check your loan papers or Key Facts Statement for early closure terms and any charge before you sign, so you know your options if you want to pay it off sooner.
Does a lithium battery increase the EMI?
Yes. On Omaha models, lithium typically costs ₹10,000 to ₹15,000 more than lead-acid, so the loan amount and EMI rise, and that extra amount also attracts interest. If you can charge at a ground-floor socket, lead-acid keeps the EMI smaller.
About this guide, and its limits
Written by the product team at Omaha Electric, a unit of JVG Electric Private Limited, which manufactures electric scooters and loaders in Hisar, Haryana. We make the scooters mentioned here, so weigh our view accordingly.
Not financial advice. We are not a bank, lender or financial adviser. This guide explains common loan terms so you can compare offers yourself. Interest rates, fees, eligibility and documents are set by each lender; rely on your lender’s Key Facts Statement and loan agreement.
About finance offers. Finance options and festive schemes vary by dealer, city and lender. Nothing here is a promise of a specific plan, rate or approval.
About the stories. The “From the showroom floor” examples are composite illustrations of common enquiry patterns, not individual customers’ accounts.
Questions — contact us, message us on WhatsApp, or book a test ride.